Moving
Moving to a new address or outside your plan's service area may create a Special Enrollment Period.
Medicare has several enrollment periods, and each one serves a different purpose. The right window depends on your age, current coverage and what's happening in your life.
We'll help you understand when you can enroll, when you can make changes and which deadlines actually apply to you.
Turning 65, changing plans or experiencing a life event?
You don't need to memorize Medicare's alphabet soup. Start with your situation and we'll point you toward the enrollment window that may apply.
Your Initial Enrollment Period is generally your first chance to sign up for Medicare Part A and Part B. For most people, it is a seven-month window surrounding the month they turn 65.
Your enrollment window generally opens three months before the month you turn 65.
This is the month you generally become eligible for Medicare based on age.
Your Initial Enrollment Period generally continues for three months after your birthday month.
If you sign up for Part B before the month you turn 65, coverage generally begins the month you turn 65. If you enroll during your birthday month or during the following three months, Part B generally begins the next month.
Often called the Annual Election Period, this is the major fall enrollment window when people with Medicare can review their health and drug coverage and make changes for the next year.
You can begin making eligible Medicare health and drug plan changes.
The plan generally must receive your enrollment request by December 7.
Changes made during this enrollment period generally take effect January 1.
Premiums, copays, formularies, drug tiers, provider participation and plan benefits can change. Your own doctors, prescriptions and healthcare needs can change too.
Don't assume this year's Medicare plan is automatically the best choice for next year.
REVIEW MY MEDICARE COVERAGE →From January 1 through March 31, people already enrolled in Medicare Advantage generally have a limited opportunity to make one change.
The annual Medicare Advantage Open Enrollment Period begins.
Eligible changes generally must be made by the end of March.
Your new coverage generally begins the first day of the month after the plan receives your request.
This enrollment period is specifically for people who are already enrolled in a Medicare Advantage plan. It is not the same as fall Medicare Open Enrollment.
Certain life events and changes in coverage may create an opportunity to enroll in or change Medicare coverage outside the usual annual enrollment windows.
Moving to a new address or outside your plan's service area may create a Special Enrollment Period.
Losing qualifying employer or union coverage may create a limited opportunity to enroll in Medicare.
Gaining, losing or experiencing changes in Medicaid eligibility can affect your Medicare enrollment options.
Moving into or out of certain institutional settings may create additional Medicare enrollment opportunities.
Certain Medicare plan terminations, contract changes or service area issues may trigger special enrollment rights.
Certain changes involving Medicaid or Extra Help can create additional opportunities to change Medicare drug or health coverage.
The General Enrollment Period gives certain people who missed their earlier opportunity another chance to enroll in Medicare Part B and, when applicable, premium Part A.
The General Enrollment Period opens at the beginning of the year.
Enrollment requests generally must be made by March 31.
Coverage generally begins the month after you sign up.
Depending on your circumstances, delaying Medicare enrollment may result in a Part B or Part A late enrollment penalty. It's worth confirming whether you qualify for a Special Enrollment Period before assuming the GEP is your only option.
Federal Medigap Open Enrollment is a one-time six-month period that begins the first month you're age 65 or older and enrolled in Medicare Part B.
The federal six-month window begins once both conditions are met.
During this period, insurers generally can't deny a Medigap policy because of pre-existing health conditions.
Outside protected enrollment or guaranteed-issue situations, choices may be more limited or medical underwriting may apply.
Different enrollment windows solve different problems. This overview can help you remember which periods happen annually and which depend on your personal circumstances.
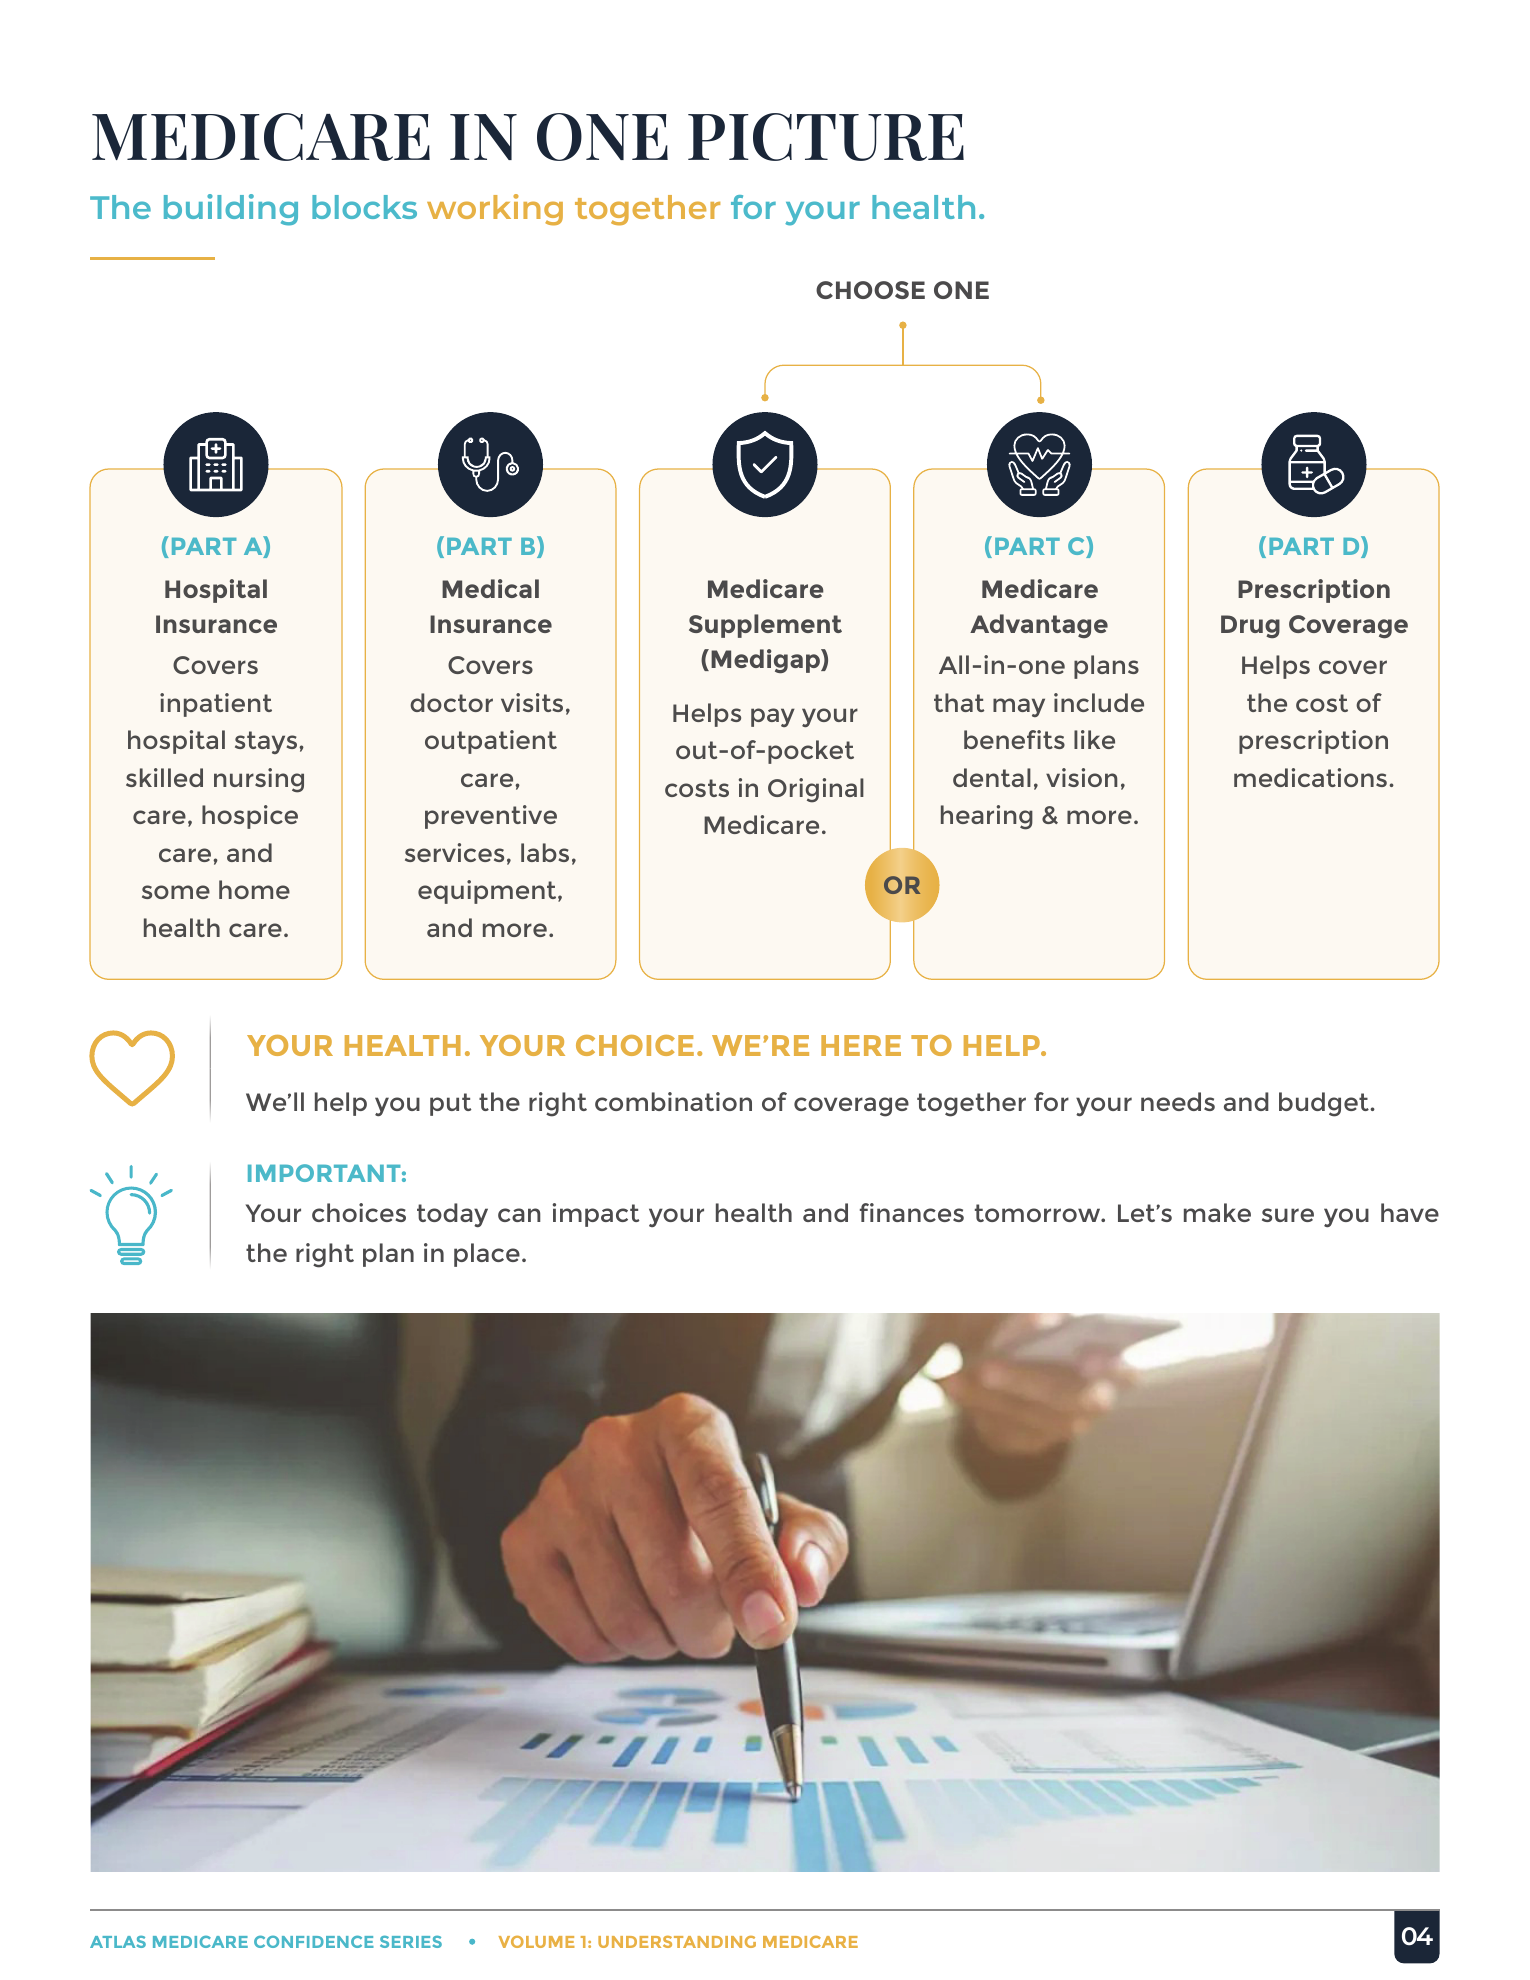
Enrollment periods determine when you can start Medicare or make certain coverage changes. See how those deadlines fit alongside Medicare Advantage, Medigap, Part D and your other Medicare choices.
Our complimentary Understanding Medicare — 2027 Edition guide walks you through Medicare in clear, straightforward language.
Tell us what's happening — turning 65, losing employer coverage, moving, reviewing your plan or simply realizing you may have missed a Medicare deadline.
We'll help you understand which enrollment window may apply and what your next step should be.
No cost. No obligation. Just clear Medicare guidance.
We may not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.